CRE
How Commercial Property Valuation Works
By Khai Tran · · 6 min read
An introduction to the income approach to commercial property valuation, with NOI, cap rate, and a hypothetical calculation explained step by step.
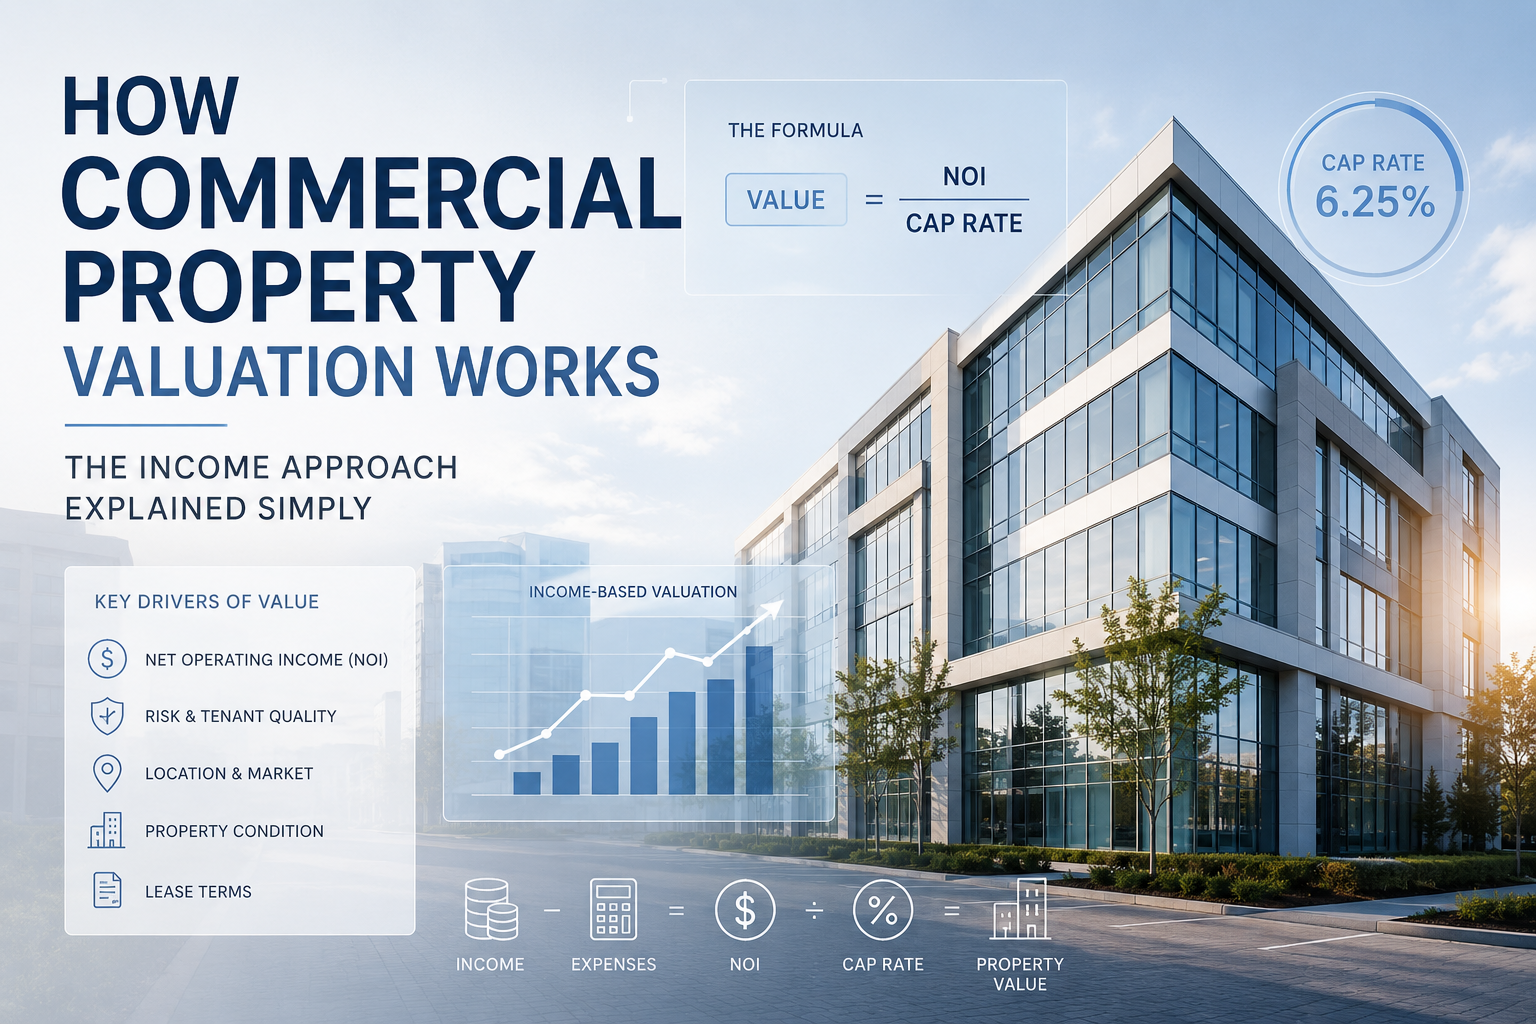
A commercial property valuation needs a clear explanation of the income, market evidence, and assumptions used. This guide focuses on the income approach and how NOI and cap rate affect the indicated value.
The Income Approach: The Foundation of CRE Valuation
The income approach is useful for income-producing property. The asset and purpose of the valuation determine the appropriate methods; sales comparisons and cost evidence may also matter.
At its core, it answers one question:
“Based on the income this property produces, what is it worth today?”
The Core Valuation Formula
The formula itself is simple:
Value = Net Operating Income (NOI) ÷ Cap Rate
Check the basis for both inputs before using the result.
Step 1: Understanding Net Operating Income (NOI)
Net Operating Income reflects how the property performs before financing.
Income That Counts Toward NOI
- Rental income
- Reimbursements (CAM, NNN, etc.)
- Parking, laundry, or other ancillary income
Expenses That Are Subtracted
- Property taxes
- Insurance
- Repairs and maintenance
- Property management
- Utilities (if owner-paid)
Items NOT Included in NOI
- Mortgage payments
- Depreciation
- Capital expenditures (typically excluded)
NOI shows the property’s true operating performance, regardless of how it’s financed.
Step 2: Cap Rates Explained (Plain English)
A cap rate compares annual NOI with price or value. It is not a total return measure, and the ratio alone cannot establish that a property is safer than another.
What Influences Cap Rates
- Tenant credit quality
- Lease length
- Property condition
- Location strength
- Market stability
- Asset type (retail, office, industrial, multifamily)
Lease duration, tenant credit, capital needs and current sales evidence can affect pricing. Examine those facts rather than assigning a risk level from the cap rate alone.
Explain the specific evidence supporting the selected cap rate.
Step 3: How Value Is Derived in Practice
Here is a hypothetical example using assumed inputs:
- Net Operating Income: $500,000
- Market cap rate: 6.5%
$500,000 ÷ 0.065 = $7,692,307
That’s the value indication.
The arithmetic shows the effect of the assumptions; it does not verify the NOI or establish the market cap rate.
Why Two Buyers Can Value the Same Property Differently
Valuation is market-based, but buyers price risk differently.
One buyer may:
- Accept a lower initial return
- See upside through rent growth
Another buyer may:
- Require stronger cash flow today
- Price more conservatively
Different assumptions can produce different estimates.
Explain the assumptions and how they affect the result.
The Role of Comparable Sales in CRE Valuation
Comparable sales still matter, but they play a different role than in residential.
In CRE, comps are used to:
- Support cap rate assumptions
- Validate income expectations
- Understand investor sentiment
Use relevant sales to examine the income assumptions and cap rate in this approach.
A Simple Script to Explain Valuation to Investors
Here’s a practical, non-salesy way to explain valuation:
“Rather than starting with price, I start with income. This property generates approximately $X in NOI. Based on comparable sales and market risk, similar assets are trading around a Y% cap rate. Applying that cap rate supports a value around $Z. From there, we can decide if the return aligns with your goals.”
Use the script only after checking the inputs and comparable evidence for the property.
Common Valuation Mistakes Agents Make
Watch for:
- Leading with price instead of income
- Quoting cap rates without explaining risk
- Ignoring expense assumptions
- Overselling upside instead of framing scenarios
Keep the sources and calculations available for review. When an input changes, show how it changes the value indication.